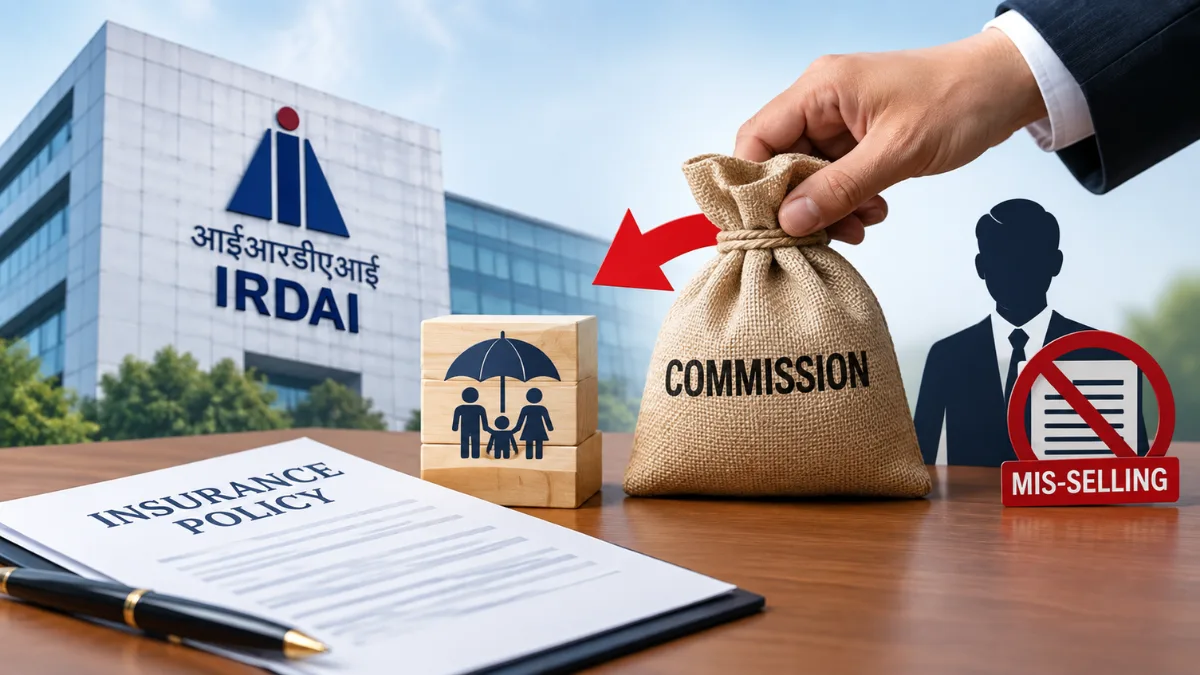
In the insurance sector, customers are often sold policies based on misleading information, and people frequently get trapped by the lure of high returns. The insurance regulator (IRDAI) is now set to take significant measures to curb this practice. If this proposal is implemented, it will help rein in fraud against customers in the insurance sector. It will particularly impact agents who mislead customers in their rush to meet sales targets.
Under IRDAI’s new proposal, the most significant change concerns agents’ commissions. Previously, if an agent sold policies by making false claims, their commission was assured regardless. However, under the new rules, if it is established that a policy was sold improperly, the commission earned by the agent or distributor will be clawed back. With this rule in place, agents will not dare to mislead customers.
Curbing Targets for Bank Employees
Often, when visiting a bank or an NBFC, employees encourage customers to purchase insurance policies, for which they receive rewards or incentives. The IRDAI has proposed putting a stop to this practice as well; bank employees will no longer be given incentives based on the number of policies sold or sales targets. This will reduce the pressure on customers to purchase unnecessary policies.
Policies cannot be sold by misrepresenting them as investment products
Agents often market insurance products by drawing parallels to fixed deposits and promising high returns. The IRDAI has stated that such practices will be classified strictly as ‘mis-selling.’ The primary objective of insurance is to provide protection; selling it under false pretenses warrants direct action. This measure will help safeguard investors’ money.